Investment Comparison | September 2026
The question has existed for 20 years. Families in South Delhi, Civil Lines, and Connaught Place’s bungalow belt have been watching Gurgaon’s DLF Camellias and Noida’s Jaypee Greens grow into what Delhi itself could not offer: the modern condominium, the professional management, the resort-scale amenities. Some of them moved. Many stayed — and watched the value of their Delhi addresses compound regardless, because Delhi addresses have a quality that no amount of Gurgaon infrastructure can manufacture: they are permanent.
The question has now been disrupted from a different direction. Delhi has, in 2026, produced five institutional-quality luxury high-rise projects simultaneously — across South, North, Central, and West Delhi. The question is no longer ‘Delhi or Gurgaon?’ It is ‘which Delhi, and for what?
Gurgaon can always build more. Noida can always build more. Delhi’s Master Plan 2041 cannot. The permanent supply constraint that makes Delhi’s Category A addresses appreciate at 14-22% annually even in a luxury floor format is the same constraint that makes the new high-rises — Kreeva Swaranya, Godrej Connaught One, Hines Kamla Nagar — the last such products in their respective micro-markets.
The Case for Delhi — What Gurgaon and Noida Cannot Offer
1. Address permanence
New Friends Colony has been Delhi’s most permanent premium residential address for 60 years. Connaught Place has been the capital’s central business and social district for 80 years. Lodhi Colony has been one of Delhi’s oldest planned residential addresses since the 1930s. Kamla Nagar has been North Delhi’s commercial and social spine for 50 years. South Delhi floor prices rose 14-32% in Q1 2026 — not because of new infrastructure, not because of an airport, but because of 60 years of compounded address permanence. Gurgaon’s Sector 58 is 15 years old. DXP’s Sector 36A is 8 years old. No amount of Oberoi Three Sixty North can make Sector 58 the social equivalent of New Friends Colony.
2. Supply constraint that DDA Master Plan makes permanent
The DDA Master Plan 2041 restricts new residential land release in Delhi. There are no new large parcels in South Delhi’s Category A colonies. There is no new Connaught Place adjacency. There is no new Lodhi Road land that RLDA will allocate again at this scale. The five projects above are not just rare — they are the last. When Kreeva Swaranya‘s 114 units and Godrej Connaught One‘s 46 units are allotted, those specific products close permanently. Gurgaon can always launch a Phase 2. Delhi cannot.
3. No dependence on infrastructure catalysts
Gurgaon’s current appreciation thesis requires Jewar Airport to open, the Metro extension to deliver, and Global City to develop. These are real catalysts — but they are future events that may be delayed. Delhi’s appreciation is not thesis-dependent. It is happening right now, without a single new infrastructure event, simply because demand exceeds supply of quality residential space in established Delhi colonies. A Delhi address appreciates in an election year, in a slowdown year, in a geopolitical uncertainty year — because the supply is permanent and the demand is permanent.
The Case for Gurgaon and Noida — What Delhi Cannot Offer
Scale and amenity infrastructure
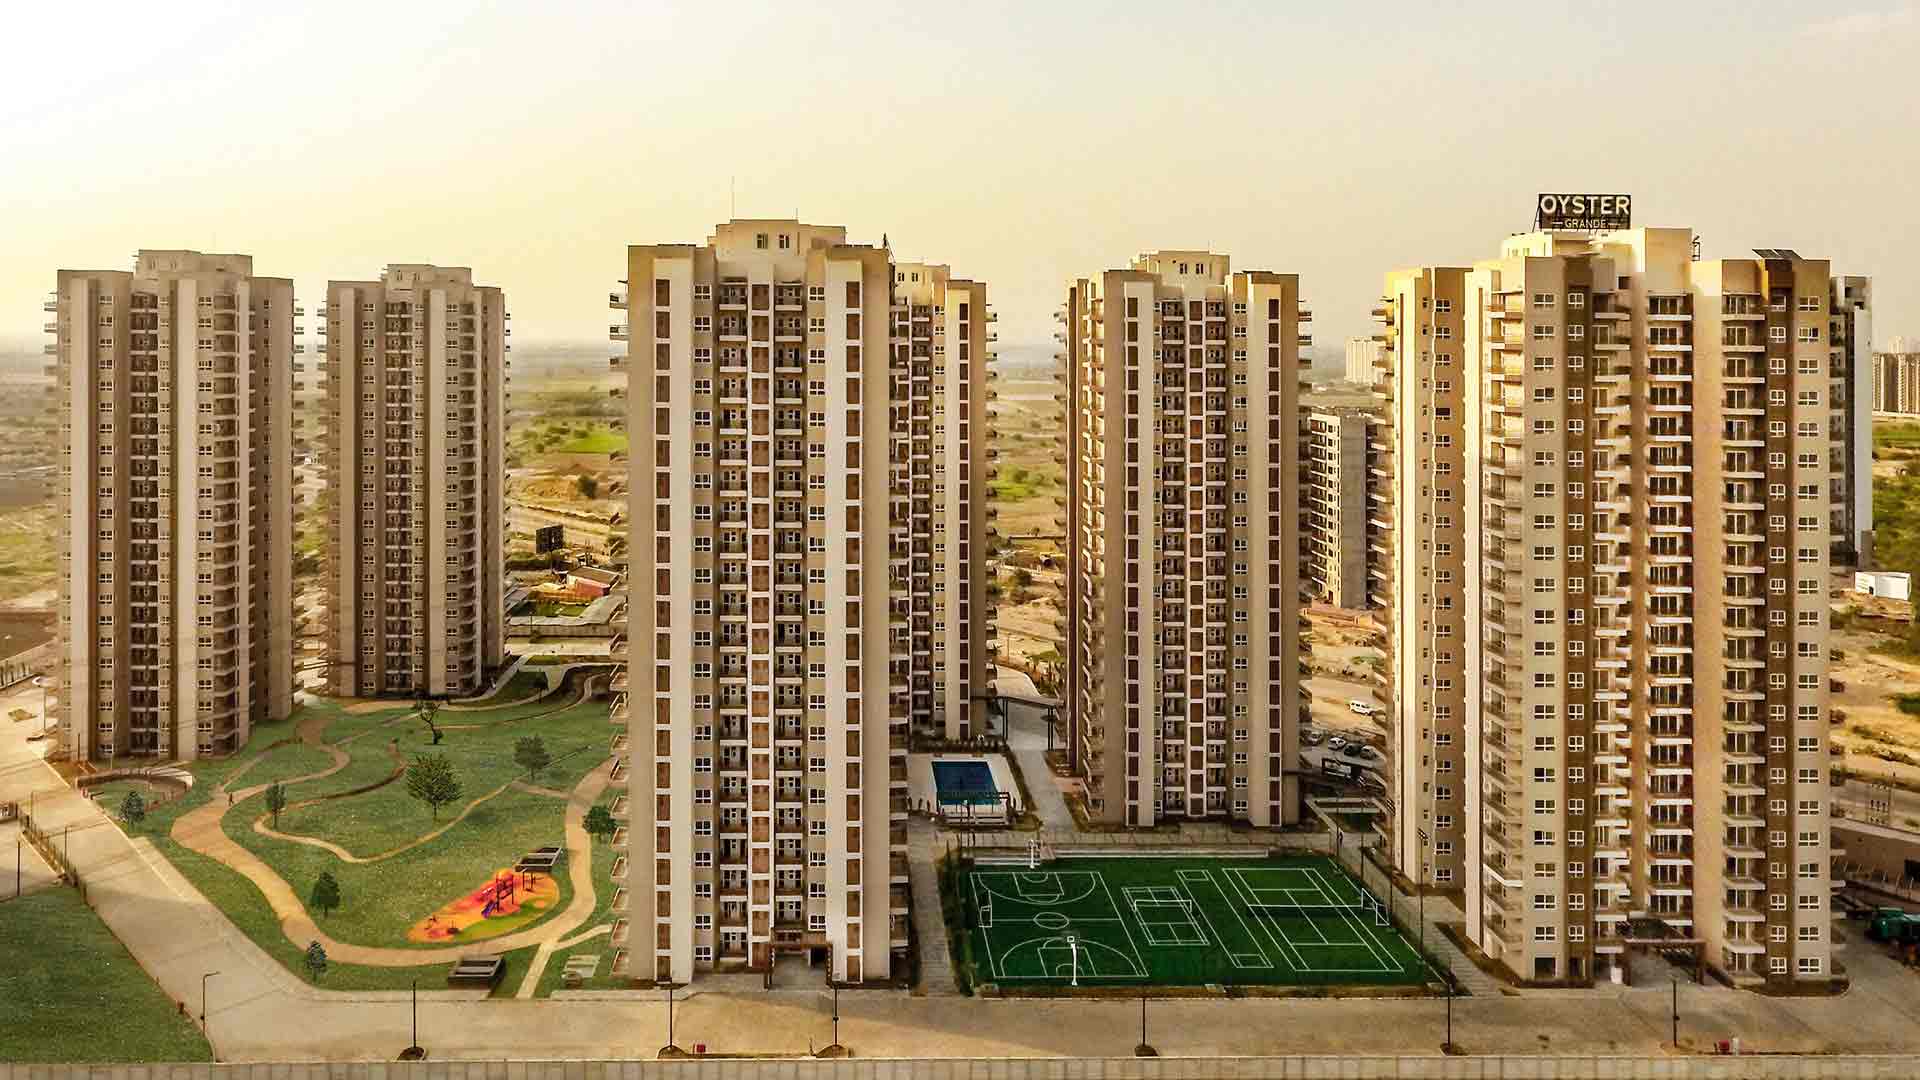
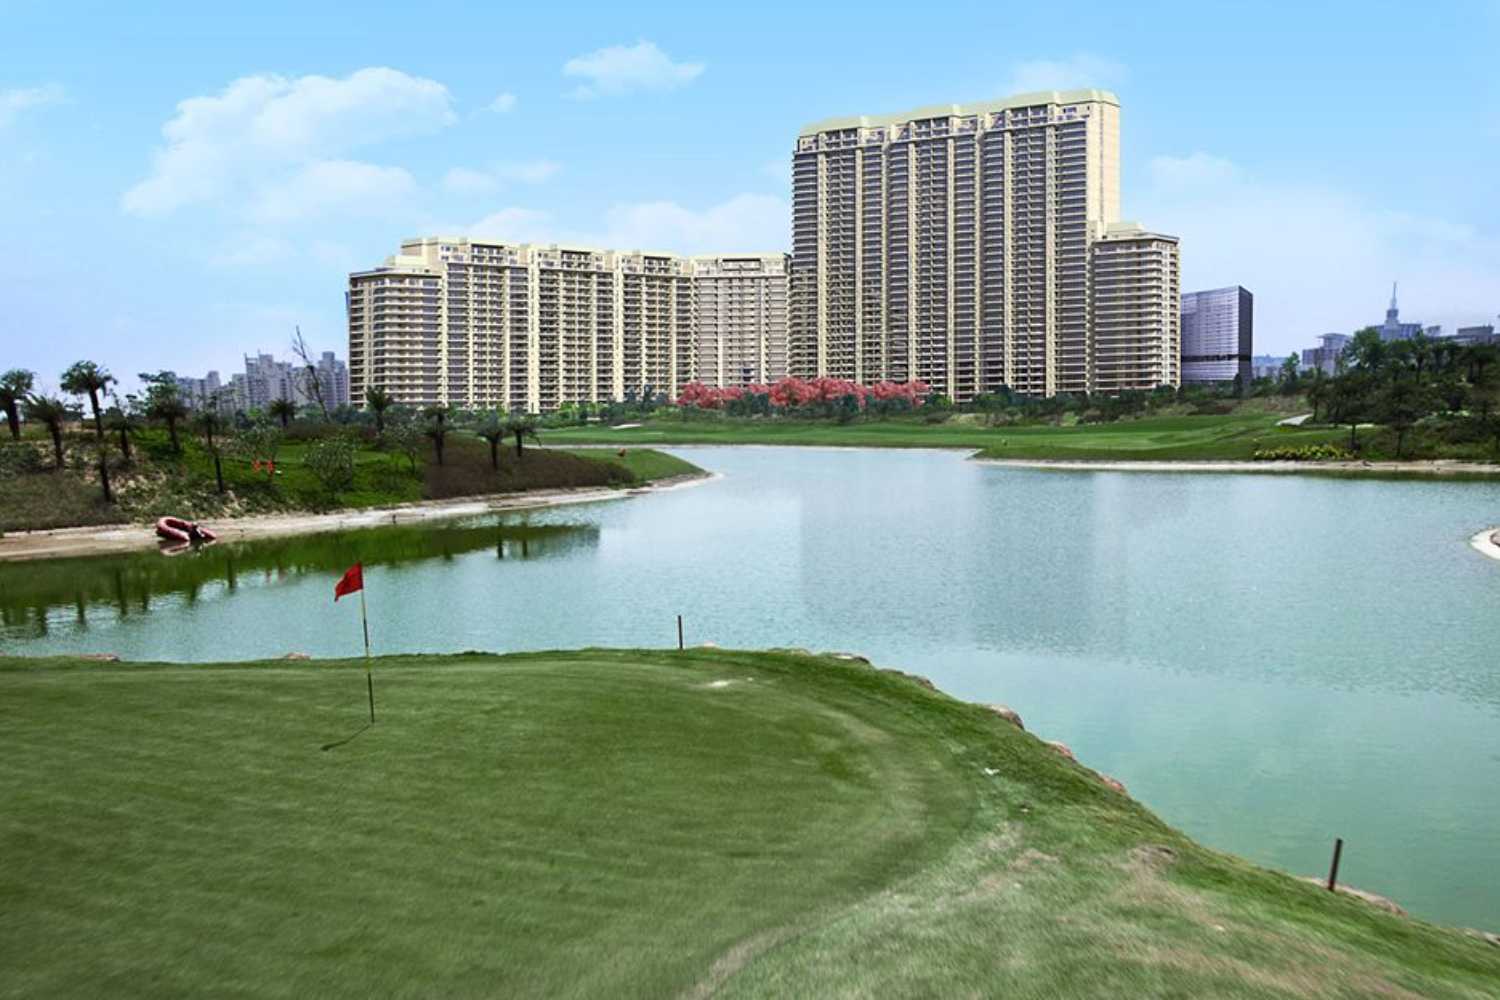
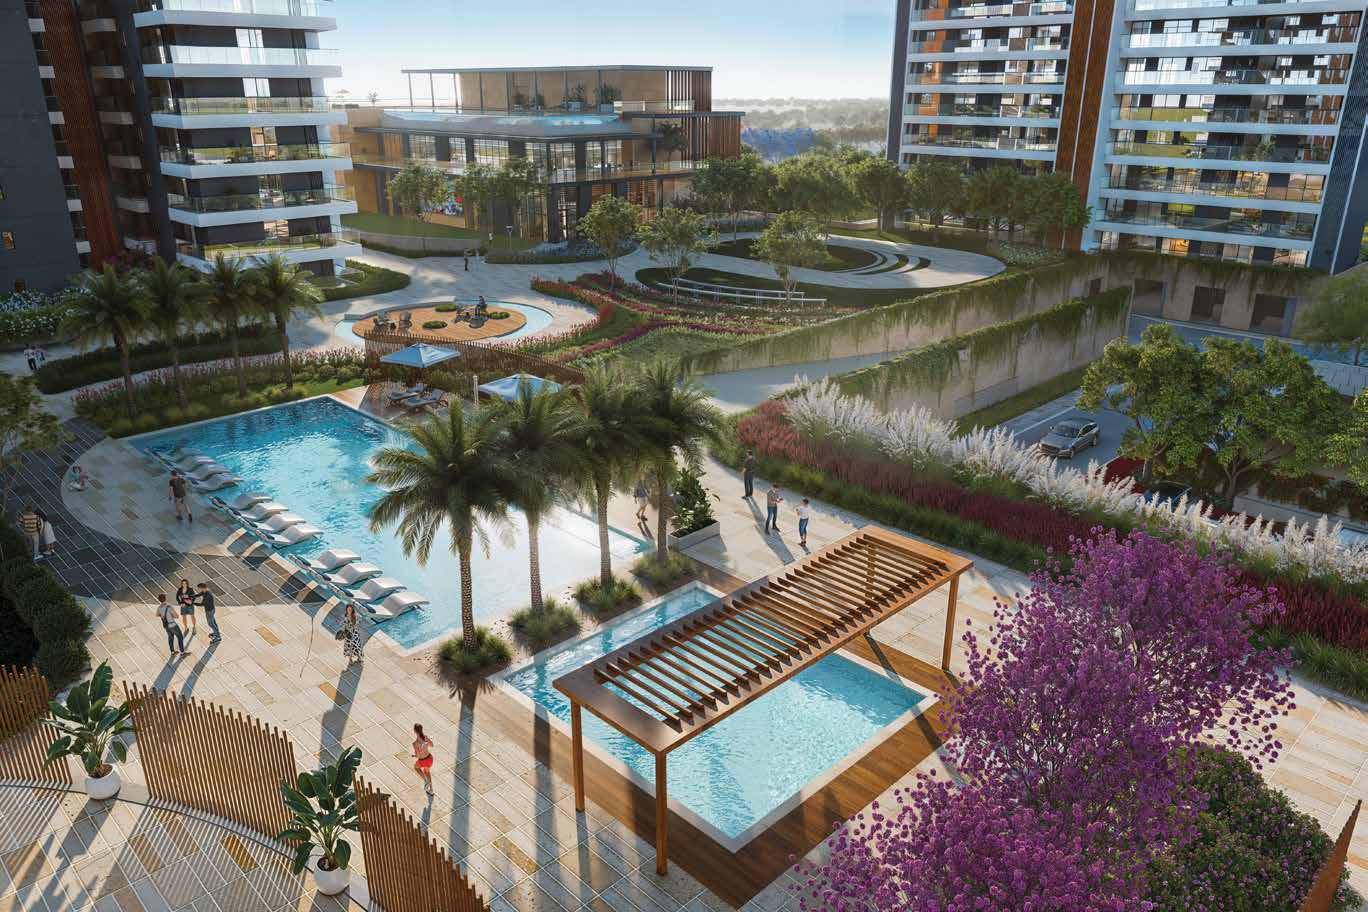
Godrej Verano’s 2 lakh sq ft of amenities for 600 families. Oberoi Three Sixty North’s one apartment per floor. Max Estate 105’s IGBC Platinum. Gurgaon and Noida’s luxury product offers amenity scale — pools, clubhouses, sports facilities, co-working spaces — that Delhi’s typically smaller land parcels cannot replicate. Kreeva Swaranya has 1,50,000 sq ft for 114 families (1,315 sq ft per family — exceptional). But DLF One Midtown has 913 units — not 114. Scale is a Gurgaon and Noida advantage.
Liquidity — more buyers, more transactions, faster appreciation cycles
Gurgaon’s luxury residential market has 8 active launches, multiple corridors, and a buyer pool drawn from India’s entire corporate executive population. The resale market is liquid — thousands of transactions annually. Delhi’s luxury high-rise market is emerging — five projects, a few hundred units, a smaller buyer pool. The Gurgaon investor who needs to exit within 3 years has more market liquidity than the Delhi investor in the same window.
Project by Project — The Honest Comparison
Kreeva Swaranya NFC (₹40,000 per sq ft) vs Oberoi Three Sixty North Phase 2 (₹40,000 per sq ft)
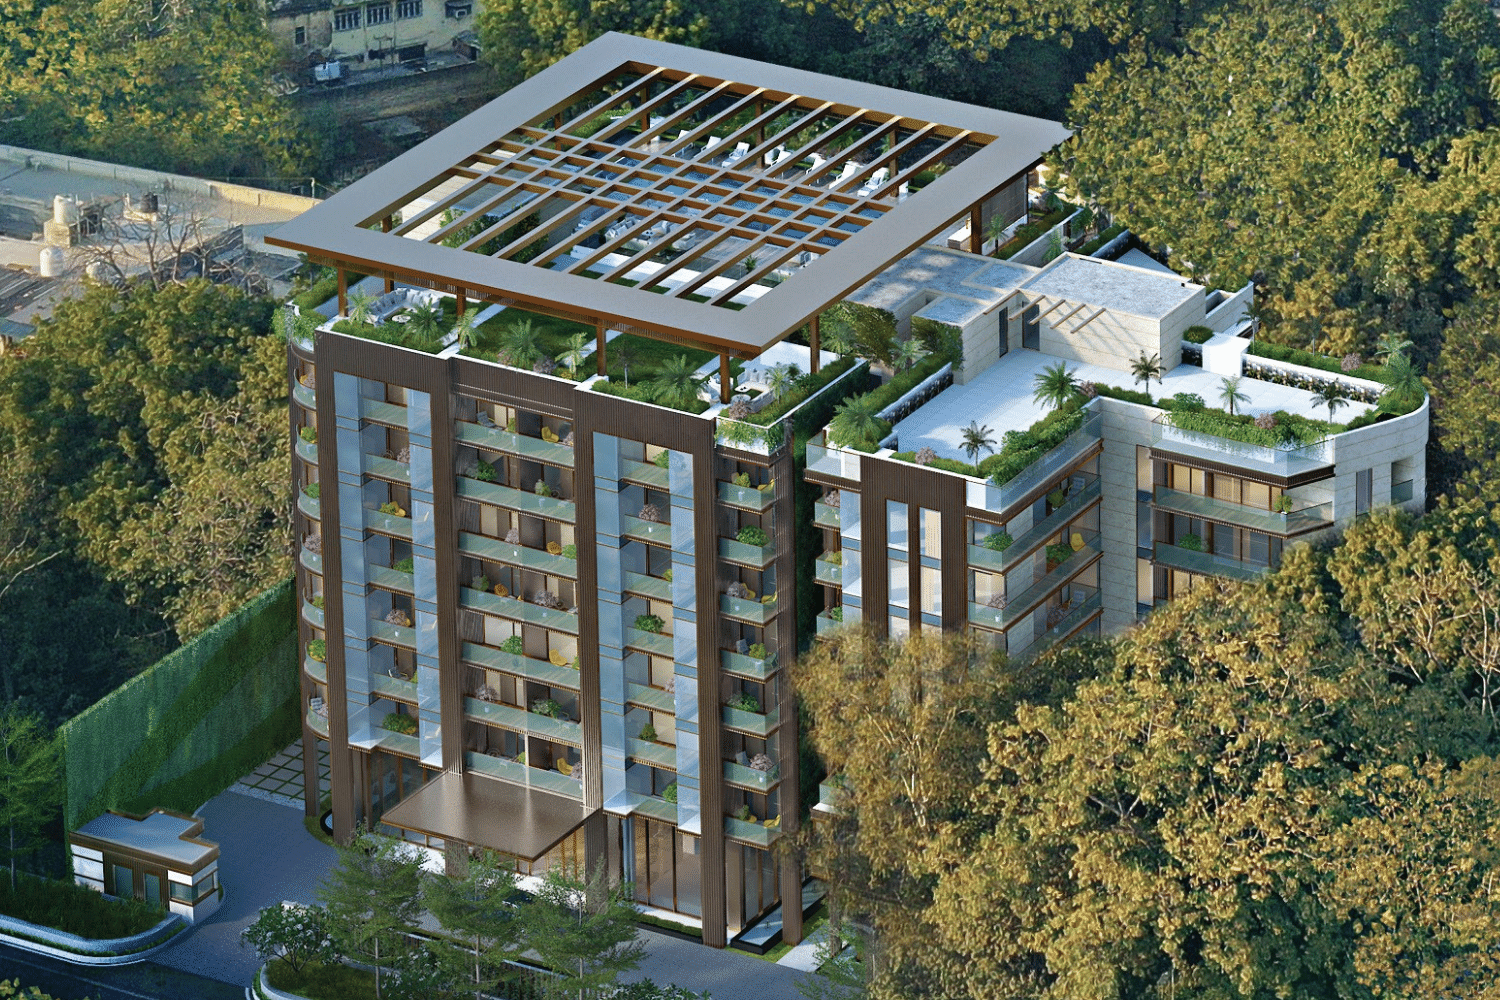
Same price per sq ft. Kreeva Swaranya NFC: 114 units, 2.5 acres NFC, 23-ft ceilings, 2 private lifts, Shapoorji Pallonji, RERA DLRERA2026P0007, 5.5 BHK at 5,100 sq ft. Oberoi Three Sixty North: 300 units, Sector 58 GCER, 1 apartment per floor, Grand Hyatt precinct, L&T construction, HC stay on fresh allotments pending. Both at ₹40,000 per sq ft. Delhi’s NFC address vs Gurgaon’s GCER address. 60 years of permanence vs 15 years of corridor momentum. 114 units vs 300. The choice is between two very different investment theses at the same entry price.
DLF One Midtown (₹25,440 per sq ft) vs Godrej Verano GCER (₹22,000-25,000 per sq ft)
Comparable price range. DLF One Midtown: 913 units, West Delhi, 128 acres greenery, GIC partnership, 3 metro stations proximity, possession July 2026, 2/3/4 BHK from ₹4.32 crore. Godrej Verano GCER: ~500 units, Sector 63A, Miami theme, 2 lakh sq ft, corner units, 3.5/4.5/5.5 BHK, December 2032 possession. DLF Midtown wins on: possession now, West Delhi address, GIC backing. Godrej Verano wins on: larger configurations, corner units, resort lifestyle, GCER appreciation corridor.
Conscient Hines Kamla Nagar (North Delhi) vs Max Estate 105 Noida (₹27,000 per sq ft)
Both institutional quality, both large-scale, both city-address products. Conscient Hines Elevate Kamla Nagar: 10 acres, Birla Cotton Mills legacy, Hines ($93B global), North Delhi permanence, 3/4/5 BHK, mixed-use retail. Max Estate 105 Noida: ₹27,000 per sq ft, IGBC Platinum, Noida Expressway, Jewar Airport 25 minutes, delivery approaching. Hines Kamla Nagar is for the North Delhi family that will not leave their neighbourhood. Max Estate 105 is for the Noida buyer who wants institutional quality before Jewar Airport’s full impact is priced in.
Superluxere’s Verdict — Not Either/Or, But Which One for Whom
- Buy Delhi if: Your family, school, social circle, and identity are rooted in Delhi. You want address permanence that no infrastructure event can undermine. You have a 10+ year horizon. You specifically want NFC, Connaught Place, Lodhi Road, Kamla Nagar, or Moti Nagar as your primary residential address.
- Buy Gurgaon if: You want the largest amenity scale, the highest appreciation momentum, the most liquid resale market, and the ability to choose from multiple corridors and price points. GCER’s Oberoi Three Sixty North validated ₹38,000-45,000 per sq ft. Sector 63A’s three launches are at ₹20,000-25,000. The range is unmatched.
- Buy Noida if: You want the Jewar Airport pre-catalyst play, the expressway’s luxury belt before Sector 150’s 15-20 launch wave reprices the corridor, and Max Estate 105’s institutional quality at ₹27,000 per sq ft with IGBC Platinum.
The buyer who genuinely cannot decide between Delhi and Gurgaon almost certainly has Delhi roots they have not fully acknowledged and should buy Delhi first.
→ Superluxere: New Delhi Luxury Projects — Complete Superluxere Coverage
→ Superluxere: Kreeva Swaranya NFC — South Delhi Analysis
→ Superluxere: Conscient Hines Elevate Kamla Nagar — North Delhi
→ Superluxere: DLF One Midtown Moti Nagar — West Delhi
→ Superluxere: All Delhi NCR luxury projects
→ Opulnz Abode: Luxury Flats in Delhi — Full Portfolio
→ Opulnz Abode: Kreeva Swaranya — Best South Delhi Investment
→ Opulnz Abode: Luxury Flats Gurugram — Gurgaon Comparison
📞 Advisory: Opulnz Abode at +91 9654888862 — Delhi vs Gurgaon advisory — one call tells you which is right for your specific situation.
Frequently Asked Questions
Is Delhi luxury real estate a better investment than Gurgaon in 2026?
Both are strong — with different investment theses. Delhi: 14-32% annual appreciation in luxury floors Q1 2026, permanent supply constraint under DDA Master Plan 2041, address permanence that does not require infrastructure catalysts. Gurgaon: highest momentum corridor (GCER 52% PSF appreciation 2025), largest amenity scale, most liquid resale market, 8 simultaneous launches from ₹13,000-40,000 per sq ft. The Delhi investor gets permanence and address prestige. The Gurgaon investor gets scale and momentum. Full coverage at Superluxere’s Delhi projects page.
Which Delhi luxury project has the best investment case in 2026?
By zone: South Delhi — Kreeva Swaranya NFC at ₹40,000 per sq ft (114 units, last such project in NFC permanently). North Delhi — Conscient Hines Elevate Kamla Nagar (10 acres, Hines’ Delhi debut, Birla Cotton Mills legacy site). Central Delhi — Godrej Connaught One (46 units, delivered, Connaught Place — most irreplaceable address). Lodhi Road — Galaxy Lodhi Greens (RLDA land, Lodhi Colony, ₹1,000 crore). West Delhi — DLF One Midtown (913 units, GIC, possession July 2026, ₹25,440 per sq ft).
Sources: Superluxere Research | Golden Growth Fund Q1 2026 | DDA Master Plan 2041 | DLF | Godrej Properties | Hines | KREEVA | RLDA | Superluxere Research September 2026Superluxere: New Delhi Luxury Projects | Opulnz Abode: opulnzabode.com/luxury-flats-in-delhi | Book: +91 9654888862